


|
STATE BANK OF VIETNAM |
SOCIALIST REPUBLIC OF VIETNAM |
|
No. 04/2026/TT-NHNN |
Hanoi, March 31, 2026 |
ON GUIDANCE FOR CERTAIN ASPECTS OF DEPOSIT INSURANCE ACTIVITIES
Pursuant to the Law on the State Bank of Vietnam No. 46/2010/QH12;
Pursuant to the Law on Deposit Insurance No. 111/2025/QH15;
Pursuant to Decree No. 26/2025/ND-CP of the Government on functions, duties, powers and organizational structure of the State Bank of Vietnam;
At the proposal of the Director of the Department of Credit Institution System Safety;
The Governor of the State Bank of Vietnam hereby promulgates a Circular on guidance for certain aspects of deposit insurance activities.
This Circular provides elaboration of clause 5 Article 14, clause 1 Article 19, clause 8 Article 19, clause 3 Article 29, clause 3 Article 33 of the Law on Deposit Insurance; and provides regulations on: This Circular provides elaboration of clause 5 Article 14, clause 1 Article 19, clause 8 Article 19, clause 3 Article 29, clause 3 Article 33 of the Law on Deposit Insurance; and provides regulations on: deposit insurance premiums, payment of deposit insurance, opening and use of accounts of Deposit Insurance of Vietnam (DIV) at payment service providers, and examination activities in accordance with the plans and scope assigned by the State Bank of Vietnam (hereinafter referred to as the State Bank).
This Circular applies to the following entities:
1. Deposit Insurance of Vietnam (DIV).
2. Member institutions of the deposit insurance scheme (hereinafter referred to as member institutions), including: commercial banks, foreign bank branches, cooperative banks, people’s credit funds and microfinance institutions.
3. Insured depositors.
4. Other organizations and individuals related to deposit insurance activities.
Article 3. Deadline for payment of deposit insurance premiums
1. Deposit insurance premiums are calculated and paid periodically on a quarterly basis within the financial year. Member institutions must calculate and pay deposit insurance premiums to DIV no later than the 20th day of the first month of the premium collection quarter. Where the last day of the premium payment deadline falls on a public holiday, Lunar New Year holiday or weekend, the member institution may make the payment on the next working day immediately following such holiday or weekend.
2. Within 15 days from the expiry of the deposit insurance premium payment deadline prescribed in clause 1 of this Article, DIV shall be responsible for providing written notification on the calculation and payment of deposit insurance premiums to the member institution, clearly stating any collection of underpaid premium or refund of overpaid premium (if any). The member institution shall be responsible for paying the outstanding premium amount, and DIV shall be responsible for refunding the overpaid premium amount (if any) within a maximum of 15 days from the date of the notification.
3. Where inaccuracies are detected in the calculation and payment of deposit insurance premiums, DIV shall proceed in accordance with clause 2 Article 20 of the Law on Deposit Insurance.
Article 4. Calculation of deposit insurance premiums
1. Deposit insurance premiums are calculated on the average insured deposit balance of insured deposit types at the member institution at the following rates:
a) 0.15%/year, except for cases prescribed in points b and c of this clause;
b) 0.1%/year for people’s credit funds;
c) Other rates pursuant to a decision of the Governor of the State Bank as prescribed in clause 11 of this Article.
2. The basis for calculating the deposit insurance premium for the premium collection quarter is the total average insured deposit balance of insured deposit types at the member institution for the quarter immediately preceding the premium collection quarter.
3. The deposit insurance premium payable for the premium collection quarter is calculated using the following formula:

Where:
– P: is the deposit insurance premium payable for the premium collection quarter.
– S0: is the insured deposit balance at the beginning of the first month of the quarter immediately preceding the premium collection quarter.
– S1, S2, S3: are the insured deposit balances at the end of the first, second and third months of the quarter immediately preceding the premium collection quarter.
– m: is the deposit insurance premium rate payable as prescribed in clause 1 of this Article.
4. Where a member institution calculates and pays premiums for the first premium collection quarter of participation in the deposit insurance scheme, the following formula shall apply:
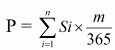
Where:
– P: is the deposit insurance premium payable for the first premium collection quarter.
– Si: is the insured deposit balance on day i (i = 1 → n; S1 is the insured deposit balance at the end of the first day of receiving deposits; Sn is the insured deposit balance at the end of the quarter immediately preceding the first premium collection quarter).
– m: is the deposit insurance premium rate payable as prescribed in clause 1 of this Article.
5. Where there is a decision on placement under special control, the deposit insurance premium payable is calculated using the formula prescribed in clause 4 of this Article; where Si is the insured deposit balance on day i (i = 1 → n); S1 is the insured deposit balance at the end of the first day of the quarter in which the decision on placement under special control comes into force; Sn is the insured deposit balance at the end of the last day before the decision on placement under special control comes into force.
6. Where there is a decision on termination of special control to resume normal operations, the deposit insurance premium payable is calculated using the formula prescribed in clause 4 of this Article; where Si is the insured deposit balance on day i (i = 1 → n); S1 is the insured deposit balance at the end of the day immediately following the day on which the decision on termination of special control comes into force; Sn is the insured deposit balance at the end of the last day of the quarter in which the decision on termination of special control comes into force.
7. A member institution formed after a merger or consolidation shall apply the deposit insurance premium calculation formula prescribed in clause 3 of this Article, where S0 is the total insured deposit balance at the beginning of the first month of the quarter immediately preceding the premium collection quarter of the member institutions participating in the merger or consolidation; S1, S2, S3 are the total insured deposit balances at the end of the first, second and third months of the quarter immediately preceding the premium collection quarter of the member institutions participating in the merger or consolidation and the member institution formed after the merger or consolidation.
8. Where a member institution terminates special control and undergoes a merger or consolidation within the same quarter, the member institution formed after the merger or consolidation shall apply the premium calculation formula P = P1 + P2 + P3.
Where:
P1 is calculated using the formula prescribed in clause 4 of this Article; where S1 is the insured deposit balance at the end of the day immediately following the day on which the decision on termination of special control of the member institution under special control comes into force; Sn is the insured deposit balance at the end of the day immediately preceding the day on which the merger or consolidation decision of the member institution under special control comes into force.
P2 is calculated using the formula prescribed in clause 4 of this Article; where S1 is the insured deposit balance at the end of the first day of the quarter immediately preceding the premium collection quarter of the member institution not under special control participating in the merger or consolidation; Sn is the insured deposit balance at the end of the day immediately preceding the day on which the merger or consolidation decision of the member institution not under special control participating in the merger or consolidation comes into force.
P3 is calculated using the formula prescribed in clause 4 of this Article; where S1 is the insured deposit balance at the end of the day on which the merger or consolidation decision of the member institution formed after the merger or consolidation comes into force; Sn is the insured deposit balance at the end of the quarter immediately preceding the premium collection quarter of the member institution formed after the merger or consolidation.
9. A member institution formed after a separation shall apply the deposit insurance premium calculation formula prescribed in clause 4 of this Article; where S1 is the insured deposit balance at the end of the opening day of operations, and Sn is the insured deposit balance at the end of the quarter immediately preceding the quarter of the first premium payment.
10. A member institution formed after a division shall calculate deposit insurance premiums using the formula P = P1 x T + P2. Where:
P1 is calculated using the formula prescribed in clause 4 of this Article; where S1 is the insured deposit balance at the end of the first day of the quarter immediately preceding the premium collection quarter of the member institution prior to division; Sn is the insured deposit balance at the end of the day immediately preceding the day on which the member institution formed after the division opens for operations of the member institution prior to division.
T is the ratio of the insured deposit balance of the member institution formed after the division to the insured deposit balance of the member institution prior to division at the time of division.
P2 is calculated using the formula prescribed in clause 4 of this Article; where S1 is the insured deposit balance at the end of the opening day of operations of the member institution formed after the division; Sn is the insured deposit balance at the end of the quarter immediately preceding the premium collection quarter of the member institution formed after the division.
11. Where DIV borrows a special loan from the State Bank to pay deposit insurance, the Governor of the State Bank shall consider and decide on increasing the deposit insurance premium rate on the basis of the deposit insurance premium rate increase plan proposed by DIV in accordance with clause 3 Article 19 of the Law on Deposit Insurance.
Article 5. Deferral of deposit insurance premium payment
1. Upon receipt of a decision on placement of a credit institution under special control or a decision on extension of the special control period, DIV shall request the member institution to calculate the outstanding, late-paid deposit insurance premium amounts and late payment charges (if any) that arose prior to the time the member institution was placed under special control.
2. No later than 10 working days from the date of receipt of DIV’s request, the member institution shall be responsible for sending a written document to DIV on the outstanding, late-paid deposit insurance premium amounts and late payment charges (if any) that arose prior to the time the member institution was placed under special control.
3. Within 5 working days from the date of receipt of the member institution’s written document, DIV shall be responsible for confirming the deposit insurance premium amount of the member institution that is deferred.
4. The member institution under special control shall be responsible for developing a plan to fully repay the deferred amount in the restructuring plan submitted to the competent authority for approval, and sending the approved plan to DIV.
Article 6. Insurance payout amount
1. The insurance payout amount for all insured deposits of one person at one member institution, including principal and interest accrued up to the triggering time of deposit insurance payout, shall be at most equal to the deposit insurance coverage limit prescribed in Article 22 of the Law on Deposit Insurance. The insurance payout amount in cases of jointly-owned insured deposits shall be implemented in accordance with clause 2 Article 23 of the Law on Deposit Insurance.
2. Where the insured depositor has a debt at the member institution, the insured deposit amount is the remaining amount after deducting the debt (including outstanding principal and interest receivable).
Article 7. Procedures for payment of deposit insurance
1. Within 5 working days from the triggering time of deposit insurance payout, the member institution must send DIV an application for deposit insurance payment. The application for deposit insurance payment shall be signed by the legal representative of the member institution, and shall include:
a) A written request for deposit insurance payment in accordance with the form prescribed by DIV;
b) A list of insured depositors in accordance with the form prescribed by DIV, clearly stating the insured deposit amount and debt at the member institution (if any) of each insured depositor as of the triggering time of deposit insurance payout at the member institution; and the insurance payout amount requested for each insured depositor.
2. Within 5 working days from the date of receipt of the complete application for deposit insurance payment as prescribed in clause 1 of this Article, DIV shall conduct an examination of documents and records to determine the deposit insurance amount payable.
The member institution shall be responsible for providing documents and records as required by DIV to serve the examination and determination of the payout amount.
Where the examination of documents and records to determine the payout amount reveals signs of violations that exceed DIV’s authority to handle, DIV shall report and recommend the State Bank to consider, examine, inspect and handle the matter.
Based on the results of DIV’s examination and the application for deposit insurance payment provided by the member institution, DIV shall prepare a list of persons to receive deposit insurance payment and the insurance payout amount for each person.
3. Within 10 working days from the completion of the examination as prescribed in clause 2 of this Article, DIV must have a deposit insurance payment plan for insured depositors; publicly announce the location, time and method of deposit insurance payment in three consecutive issues of a central newspaper, a local newspaper where the member institution’s head office and branches are located, and on a Vietnamese electronic newspaper, DIV’s official website and other forms as decided by DIV.
Article 8. Opening and use of DIV’s payment accounts at payment service providers
DIV may open payment accounts at payment service providers in accordance with the State Bank’s regulations on opening and use of payment accounts at payment service providers, and may only use these accounts for payment purposes in service of DIV’s activities. Where DIV opens an account at the State Bank, DIV shall comply with the provisions of Article 9 of this Circular.
Article 9. Opening of DIV’s accounts at the State Bank
1. DIV may open accounts at the State Bank to receive special loans from the State Bank and to make deposits in accordance with point b clause 1 and clause 2 Article 29 of the Law on Deposit Insurance. DIV’s accounts shall be entitled to the interest rate determined by the Governor of the State Bank in each period.
2. The procedures for opening DIV’s accounts at the State Bank shall be implemented in the same manner as the procedures for opening payment accounts for credit institutions and foreign bank branches at the State Bank.
INVESTMENT METHODS, CONTROL AND RISK MANAGEMENT IN INVESTMENT ACTIVITIES
Article 10. Investment methods
1. DIV shall directly invest in investment activities prescribed in clause 1 Article 29 of the Law on Deposit Insurance.
2. DIV may invest by investment mandate for the following investment activities:
a) Purchase and sale of Government bonds;
b) Purchase and sale of bonds issued by commercial banks with state ownership of over 50% of charter capital and joint-stock commercial banks with over 50% of charter capital held by state-owned enterprises.
3. In cases of investment by investment mandate, DIV must clearly set out in the annual investment plan approved by the Board of Directors at least the following:
a) The necessity of investing by investment mandate;
b) Principles and criteria for selection of the investment mandate holder, where the investment mandate holder is a fund management company, securities company or commercial bank with the function of receiving investment mandates in accordance with relevant law;
c) Mandate terms: scope and products of the mandate; rights, obligations and commitments of the parties; mandate term; mandate costs; dispute resolution and other terms;
d) A plan for handling cases where the investment mandate holder fails to perform the mandate terms;
dd) Management measures to ensure control of activities within the scope of the mandate of the mandate holder;
e) Other matters (if any).
4. DIV shall decide on the selection of the investment mandate holder and sign the contract. The contract must include the provisions prescribed in points c and d clause 3 of this Article.
Article 11. Control and risk management
1. DIV shall promulgate investment regulations, risk management regulations for investment activities, internal audit regulations as prescribed in Article 12 of this Circular, and other regulations as required for control and risk management in DIV’s investment activities.
2. DIV shall carry out investments in accordance with the approved annual investment plan and semi-annual investment plan; regularly assess the implementation situation to have handling measures within its authority and report to the Board of Directors for adjustment or supplementation (where necessary).
3. DIV shall regularly update information on market conditions; investment situation; reconcile investment amounts, amounts due for recovery and the balance of each investment item and investment subject to serve control and risk management.
4. DIV must have a risk control mechanism in investment activities to promptly detect and propose preventive and risk-handling measures.
5. DIV shall make provisions for investment activities in accordance with the regulations on the financial regime applicable to deposit insurers.
Article 12. Operational regulations
1. Investment regulations, including at least the following: investment portfolio criteria; investment mandate operations; process for developing investment structure and measures to achieve the investment structure; process for developing the annual investment plan and semi-annual investment plan; procedures and documents for each investment item prescribed in clause 1 Article 29 of the Law on Deposit Insurance; reporting regime; responsibilities of relevant units and individuals.
2. Risk management regulations for investment activities, including at least the following: types of risks affecting investment activities; identification, prevention and handling of each type of risk; methods and frequency of self-examination and control for each type of risk; process for handling when risks arise; responsibilities of relevant units and individuals.
3. Internal audit regulations, including at least the following: scope, methods, process and frequency of internal audit of investment activities; coordination responsibilities of units and individuals when organizing the internal audit, process for handling internal audit recommendations, reporting regime.
Article 13. Internal audit of investment activities
On an annual basis or as required by management, DIV shall conduct internal audit of investment activities to assess compliance with legal regulations, the annual investment plan and operational regulations and processes related to investment activities.
INFORMATION PROVISION AND EXAMINATION ACTIVITIES OF DEPOSIT INSURANCE OF VIETNAM
Article 14. Information provision
1. Member institutions shall be responsible for establishing, updating and fully and accurately maintaining truthful information as prescribed in Annex I and Annex II issued together with this Circular.
2. DIV shall ensure the safety and confidentiality of information and data in accordance with legal regulations.
3. On a monthly and quarterly basis, member institutions shall provide information to DIV in accordance with Annex II issued together with this Circular, except for Form 02b/BHTG, 02b1/BHTG, 02b2/BHTG which are provided in certain specific cases prescribed in Annex II.
4. For purposes of preparing deposit insurance payment or other cases related to deposit insurance payment at DIV’s request, member institutions shall be responsible for providing detailed customer lists and related data in accordance with Annex I issued together with this Circular. The information provision deadline shall be no more than 5 working days from the date of receipt of the request.
5. Member institutions shall provide information on insured deposits on an ad hoc basis as required by DIV’s written request.
6. For purposes of serving DIV’s examination activities, member institutions shall be responsible for providing information as required by DIV’s written request. Member institutions have the right to refuse to provide information not related to the examination scope.
7. DIV shall guide member institutions on the methods and forms of information provision.
Article 15. Examination of member institutions in accordance with plans and scope assigned by the State Bank
1. DIV shall be responsible for conducting examinations of member institutions in accordance with the State Bank’s plans and scope as prescribed in clause 10 Article 14 of the Law on Deposit Insurance, specifically as follows:
a) DIV shall be responsible for developing, promulgating, amending and supplementing the regulations on examination of member institutions as prescribed in point b of this clause, and sending them to the State Bank for opinions before such regulations are promulgated or amended. Within 7 working days from the date of promulgation or amendment, DIV must send the regulations on examination of member institutions to the State Bank and member institutions;
b) The regulations on examination of member institutions must be approved by the Board of Directors and must include at least the following:
(i) Examination principles;
(ii) Examination implementation process;
(iii) Responsibilities of the head of the examination team, examination team members; each department and division under DIV and related parties.
2. Within 7 working days from the date of completion of examination results as prescribed in clause 1 of this Article, DIV shall:
(i) Report examination results of foreign bank branches subject to micro-level supervision by the regional branch of the State Bank to that regional branch of the State Bank;
(ii) Report examination results of people’s credit funds to the regional branch of the State Bank where the people’s credit fund has its head office;
(iii) Report examination results of other member institutions to the State Bank Inspectorate.
3. DIV shall be responsible for cooperating with the State Bank in developing plans and examination scope for member institutions.
4. Before January 30 each year, the State Bank shall assign examination plans and scope for member institutions to DIV. The examination plan shall include at least the following:
a) List of member institutions subject to examination;
b) Examination scope;
c) Examination period and reporting deadline for examination results;
d) Examination implementation guidelines (if necessary).
Article 16. Responsibilities of units under the State Bank
1. Department of Credit Institution System Safety:
a) Supervise DIV in its compliance with legal regulations on deposit insurance;
b) Take charge and cooperate with relevant units to advise the Governor of the State Bank on consideration and decision on increasing the deposit insurance premium rate as prescribed in clause 11 Article 4 of this Circular;
c) Cooperate with the State Bank Inspectorate in performing the tasks prescribed in point c clause 2 of this Article.
2. State Bank Inspectorate:
a) Inspect, examine, handle violations and resolve complaints and denunciations regarding deposit insurance in accordance with the Law on Deposit Insurance;
b) Inspect and examine DIV in its compliance with legal regulations on deposit insurance;
c) Take charge and submit to the Governor of the State Bank for assignment to DIV to conduct examinations of member institutions; provide opinions on and receive the regulations on examination of member institutions as prescribed in Article 15 of this Circular.
3. Monetary Policy Department:
Take charge and cooperate with relevant units to advise the Governor of the State Bank on deciding the deposit interest rate of DIV at the State Bank.
4. Transaction Office:
Guide DIV in making deposits at the State Bank and purchasing State Bank bills in accordance with this Circular and other applicable legal regulations.
5. Regional branches of the State Bank:
a) Inspect, examine, handle violations and resolve complaints and denunciations regarding deposit insurance in the local area;
b) Cooperate with the State Bank Inspectorate in performing the tasks prescribed in point c clause 2 of this Article.
1. This Circular comes into force from May 1, 2026, except for the provisions in clause 2 of this Article.
2. The deposit insurance premium rate for people’s credit funds as prescribed in point b clause 1 Article 4 of this Circular shall be applied from the premium collection quarter of Quarter IV of 2026.
3. From the date this Circular comes into force, Circular No. 24/2014/TT-NHNN dated September 6, 2014 of the Governor of the State Bank of Vietnam on guidance for certain aspects of deposit insurance activities shall cease to be effective.
Article 18. Responsibilities for implementation
Heads of units under the State Bank, member institutions and Deposit Insurance of Vietnam (DIV) shall implement this Circular.
|
PP. GOVERNOR Doan Thai Son |

