


|
GOVERNMENT OF VIETNAM |
SOCIALIST REPUBLIC OF VIETNAM |
|
No. 230/2025/ND-CP |
Hanoi, August 19, 2025 |
DECREE
On other cases where land levies or land rents are exempt in accordance with the provisions of clause 2 Article 157 of the 2024 Land Law
Pursuant to Law on Government Organization No. 63/2025/QH15;
Pursuant to Land Law No. 31/2024/QH15 amended by Law No. 43/2024/QH15, Law No. 47/2024/QH15, Law No. 58/2024/QH15, Law No. 71/2025/QH15, Law No. 84/2025/QH15, Law No. 93/2025/QH15 and Law No. 95/2025/QH15;
Pursuant to the Law on Tax Administration No. 38/2019/QH14 amended by Law No. 56/2024/QH15;
Pursuant to Resolution No. 1636/NQ-UBTVQH15 of the Standing Committee of the National Assembly of Vietnam on other cases where land levies or land rents are exempt in accordance with the provision of clause 2 Article 157 of the 2024 Land Law (including land rent reduction of 2025);
At the request of the Minister of Finance;
The Government hereby promulgates a Decree on other cases where land levies or land rents are exempt in accordance with the provisions of clause 2 Article 157 of the 2024 Land Law.
Article 1. Governing scope
This Decree provides for other cases where land levies or land rents are exempt in accordance with the provision of clause 2 Article 157 of the 2024 Land Law (including land rent reduction of 2025);
Article 2. Regulated entities
Regulatory agencies, land users and other entities involved in the exemption or reduction of land levies or land rents in accordance with this Decree.
Article 3. Principles, procedures for exemption or reduction of land levies or land rents
1. The principles of exemption and reduction of land levies or land rents for the cases specified in this Decree shall be implemented according to the provisions of Article 157 of the Land Law 2024; Article 17, Article 38 of Decree No. 103/2024/ND-CP dated July 30, 2024 of the Government stipulating land levies and land rents.
2. The land levy exemption in the case of allocation of resettlement land shall comply with the provisions of Decrees on recompense, support and resettlement upon land repossession by the State, except for the cases specified in clause 1 Article 4 of this Decree.
3. The land rent exemption or reduction for projects to build office premises of foreign diplomatic missions or foreign consulates and representative offices of Vietnam-based international organizations according to the international treaties to which Vietnam is a signatory shall comply with the signed treaties or be in accordance with the principle of reciprocity.
4. The sequence, procedure and authority for exemption or reduction of land levies or land rents for cases specified in this Decree shall comply with the provisions of Articles 18, 19, 21, 39, 40, and 41 of Decree No. 103/2024/ND-CP.
5. The persons having authority to decide land allocation or land lease under Article 123 of the 2024 Land Law shall decide the exemption of land levies or land rents when making decisions on land allocation, land lease, land repurposing or recognition of land use rights for entities corresponding to those under the jurisdiction of land allocation or lease as prescribed in this Decree, except for the cases specified in Clauses 3, 5, and 6 of Article 5 of this Decree; including a clear statement of content: the reason for the exemption; the area of land exempted from land levies or land rents; the duration for which land rents are exempted. In cases of exemption from land rents as stipulated in clauses 3, 5 and 6 of Article 5 of this Decree, the tax authorities shall decide the exemption from land rents in accordance with regulations.
6. In cases where exemption from land levies or land rents is granted according to the provisions of this Decree, land users are not required to carry out the procedure for requesting exemption from land levies or land rents; they only need to provide information to competent authorities regarding their eligibility for such exemption as stipulated in this Decree.
7. In cases where this Decree provides regulations on the principles, procedures and authority for exemption or reduction of land levies or land rents that differ from the provisions of Decree No. 103/2024/ND-CP, the provisions of this Decree shall apply.
Article 4. Exemption or reduction of land levies
1. Land levies shall be exempt for the area of land allocated within the homestead land allocation limits in the following cases:
a) Allocating resettlement land or allocating land to households or individuals in residential clusters or areas in flood-prone regions in accordance with the decision of the Prime Minister regarding the adjustment and supplementation of beneficiaries and the mechanisms for borrowing funds for housing construction under the program for building residential clusters or areas and housing in areas regularly affected by flooding in the Mekong Delta.
b) Allocating homestead land to the fishing households and those living on rivers and lagoons who are relocated to resettlement areas or points according to the plans and projects approved by competent authorities.
2. A 30% reduction in the annual land levy shall be applied in cases of using land for both defense and production and economic construction purposes as specified in Clause 2, Article 201 of the 2024 Land Law, Decree No. 102/2024/ND-CP dated July 30, 2024 of the Government elaborating the Land Law; To be specific:
a) The Minister of National Defense is responsible for assigning the relevant authorities to calculate the reduced land levies and record them in the financial obligation notices of the Ministry of National Defense sent to the units and state-owned enterprises managed by the Ministry of National Defense; assigning the relevant authorities to guide the collection and payment of annual land levies in accordance with the provisions of Decree No. 102/2024/ND-CP and this Decree for the units and state-owned enterprises managed by the Ministry of National Defense.
b) In cases where inspections reveal that users of land for both defense and production and economic construction purposes do not use land in accordance with the land use plans approved by the competent authorities, they must make the payment of the annual land levies that was previously reduced in accordance with regulations.
3. The exemption or reduction of land levies in necessary cases to implement socio-economic policies, stabilize the macro economy, support production and business development, ensure social welfare, and address arising issues in the practical management of socio-economic affairs annually shall be carried out as follows: On the basis of the tasks and solutions outlined in the socio-economic development plans issued by the competent authorities or the tasks assigned by the competent authorities, the Ministry of Finance shall submit to the Government regulations on the exemption or reduction of land levies for one year according to the provisions of this clause.
Article 5. Land rent exemption or reduction
1. Land rents shall be exempt for the entire land lease term for the following cases:
a) Using land for the construction of the headquarters of the Vietnam Bank for Social Policies (VBSP) (including: the main office/headquarters, transaction offices, training centers, educational facilities, information technology centers, branches, transaction rooms and any other subordinate units if applicable).
b) Using land for the construction of the headquarters of the Vietnam Development Bank (VDB) (including: the main office/headquarters, transaction offices, training centers, educational facilities, information technology centers, branches, transaction rooms and any other subordinate units if applicable).
c) Using of land for the construction of headquarters for state extra-budgetary financial trusts established under the regulations of the Government and the Prime Minister that operate not for profit purposes (including: the headquarters, branches, transaction offices, and other affiliated units if any).
d) Using land for the construction of Commune-level Post Offices – Cultural Centers.
dd) Using land for the construction of scientific research facilities of science and technology enterprises if they meet the conditions stipulated by the law on science and technology, including: land for the construction of laboratories, land for the establishment of scientific and technology and technological enterprise incubation facilities, land for the construction of experimental facilities, land for the construction of pilot production facilities.
e) Exemption from land rents for the entire lease term for land belonging to units operating in the field of digital technology industry, including: Institutes, Innovation Centers for Research and Development of Digital Technology; land belonging to projects to manufacture key digital technology products, software products, semiconductor chips, and artificial intelligence products.
g) Exemption from land rents for the entire land lease term for land for the construction of concentrated digital technology zones (Investors in infrastructure for concentrated digital technology zones shall not include the exempted land rents in the rents for infrastructure within the concentrated digital technology zones).
h) Exemption from land rent for the entire land lease term for the National Innovation Center.
i) Exemption from land rent for the entire lease term for the area of buildings and land serving foreign and diplomatic purposes allocated for public service providers (or other public service providers meeting the requirements as prescribed by law) that perform the management of buildings and land serving foreign affairs to use them for the mutual purposes, with land and houses provided at no cost, and for foreign diplomatic organizations or foreign offices to lease under the special preferential policies of the State as per the decision of the competent authority, which continues to use the land in the form of land lease as stipulated in Clause 8, Article 255 of the 2024 Land Law (or use the land in the form of land lease as regulated in Point a, Clause 3, Article 120 of the 2024 Land Law).
k) Exemption from land rent for the entire lease term for non-defense land of military units that provide public services under the model of public service providers.
2. Exemption and reduction of land rents for enterprises with agriculture and rural development projects in accordance with the Government’s regulations on mechanisms and policies to encourage enterprises to invest in agriculture and rural development.
3. The exemption or reduction of land rents for cases where land users are leased land by the State with annual land rent payments for agriculture, forestry, aquaculture or salt production purposes affected by natural disasters or fires shall be implemented as follows:
a) In cases where the land lessee is an organization subject to corporate income tax and has been engaged in production and business for three years or more, the amount of land rent eligible for exemption or reduction shall be determined based on the percentage (%) of damage. The percentage (%) of damage shall be determined based on the value of damage recorded in the year specified in the Minutes for determining extent of damage and the value of damage under the tax administration laws and the average taxable revenue over the preceding 03 consecutive years; To be specific:
a1) In cases where the percentage (%) of damage is below 40%, a reduction in land rent will be considered according to the percentage (%) corresponding to the percentage (%) of damage for the year in which the damage occurred.
a2) In the case where the percentage (%) of damage is 40% or more, the rent for the year in which the damage occurred shall be waived.
a3) The land user must submit an application for a reduction in land rent in accordance with tax management laws in order to receive a reduction in land rent as stipulated in this clause. In cases where exemption from land rent is granted, the land user is not required to carry out the procedure for requesting exemption from land rent; they only need to provide information to the tax authority regarding their eligibility for such exemption.
a4) Based on the application for a reduction in land rent from the land user or the information provided by the land user, the tax authority shall take charge and cooperate with the agencies performing state management of land, investment registration authorities, financial authorities, and other related agencies (if necessary) in conducting inspections and specifically determining the percentage (%) of damage as a basis for exemption or reduction of land rent in accordance with provisions a1, a2 in this point.
b) In cases where the land lessee is a household, individual or organization with a production and business operation period of less than 03 years, the amount of land rent is determined to be reduced based on the value of the damage after deducting the amounts supported by the State as prescribed by law, and is implemented as follows:
b1) The land user affected by natural disasters or fires shall receive a reduction in land rent corresponding to the value of the damage, after deducting the value of government support in accordance with the law; the amount that the land leesee must pay in the year in which the damage occurred shall be determined as follows:
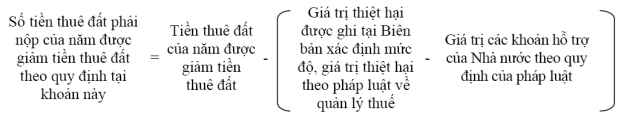
Whereas: The land rent of the year in which the land rent is reduced is the amount of land rent calculated according to the provisions of Clause 1, Article 30 of Decree No. 103/2024/ND-CP; the amount of land rent to be reduced shall not exceed the amount of land rent payable by the land user as prescribed.
b2) The land user must submit an application for a reduction in land rent to the tax authority in accordance with tax management laws in order to receive a reduction in land rent as stipulated in this clause.
b3) Based on the information regarding the value of the damage recorded in the Minutes for determining the extent and value of property damage and the application for land rent reduction according to tax management laws of the land user, the tax authority shall issue a decision to reduce land rent in accordance with the regulations.
4. The reduction of land rent for cases where a land user is leased land by the State with annual land rent payments for production and business purposes (excluding projects within which land is used for agricultural, forestry, aquaculture, and salt production purposes) but must temporarily suspend operations to mitigate the consequences of natural disasters, fires or force majeure accidents shall be as follows:
a) The period during which the land rent is reduced is the time of suspension of production and business activities as confirmed by the agency performing state management of investment registration or the agency assigned by the provincial People’s Committee to determine the period of suspension of production and business activities in accordance with the regulations.
b) The amount of land rent reduction is determined to be 50% of the land rent payable for the period during which the land rent is reduced as stipulated in point a of this clause.
c) The land user shall submit the application for land rent reduction to the tax authority in accordance with the regulations of tax management law. Based on the application for land rent reduction of the land user, the tax authority shall issue a decision to reduce land rent in accordance with regulations.
5. The exemption or reduction of land rent for organizations (including: enterprises; public service providers; cooperatives and cooperative unions operating in the fields of agriculture, forestry and fisheries that are leased land by the State with annual land rent payments for agriculture, forestry, and aquaculture production purposes (hereinafter referred to as “employing organizations or units) ) that employ a workforce comprised of ethnic minorities legally residing in provinces and central-affiliated cities, and areas with administrative boundaries that are eligible for support policies according to the Prime Minister’s Decision on supporting organizations and units employing workers from ethnic minorities in mountainous areas and particularly difficult regions, shall comply with the following regulations:
a) A 50% reduction in land rent shall be granted to organizations and units employing a workforce comprised of ethnic minorities with a percentage (%) of ethnic minorities ranging from 30% to less than 50% as determined according to the provisions set forth in point c of this clause.
b) An exemption from land rent shall be granted to organizations and units employing a workforce comprised of ethnic minorities with a percentage of ethnic minorities of 50% or more as determined according to the provisions set forth in point c of this clause.
c) The percentage of ethnic minorities used as the basis for exemption or reduction of land rent shall be determined according to the following formula:
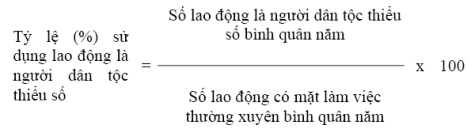
Whereas:
The average number of employed ethnic minorities in a year is determined by the total number of ethnic minorities working under labor contracts or fixed-rate product contracts lasting 12 months or longer and in the fields of agriculture, forestry and aquaculture during the 12 months of the year preceding the budgetary year (the year in which land rent payments are required), divided by 12.
The average number of the workforce present for work on a regular basis throughout the year is determined by the total number of employees present for work on a regular basis in the fields of agriculture, forestry and aquaculture over the 12 months of the year preceding the budgetary year (the year in which land rent payments are required), divided by 12.
In the case of employing organizations or units that are newly established and begin operations, the number of months in the first year shall be calculated based on the number of months they operate within that year.
d) The workforce present for work on a regular basis includes employees working according to the timekeeping records of the employing organizations or units (excluding part-time workers and employees with contracts lasting less than 12 months) and those working under fixed-rate product contracts (a fixed-rate product contract may replace a labor contract and must have a duration of 12 months or more).
dd) Ethnic minorities in fixed-rate product contracts are individuals who directly sign the fixed-rate product contracts with the employing organizations or units.
e) The exemption or reduction of land rent is based on the percentage (%) of employed ethnic minorities from the year proceeding the year in which the land rent is due.
g) Within 30 days from the date of the notification of first payment of land rent by the tax authorities (May 31 from the second year of the land lease onwards), the employing organizations or units must submit to the tax authorities the applications for a reduction in land rents in accordance with tax management laws in order to receive a reduction in land rents as stipulated in this clause. In cases of exemption from land rents, employing organizations and units are not required to carry out procedures to request an exemption from land rents; they only need to provide information about the entities eligible for land rent exemption in accordance with the provisions of this clause to the tax authorities no later than 30 days from the date of notification of land rent payment from the tax authorities. The tax authorities shall, based on the applications and information provided by the employing organizations or units, decide the land rent exemption or reduction of the employing organizations or units in accordance with this clause.
h) Annually, if the percentage of employed ethnic minorities remains unchanged or changes but does not affect the levels of land rent exemption or reduction determined by the competent authorities, the employing organizations or units are only required to submit reports on the situation of employment of ethnic minorities in the planned year to the tax authorities for monitoring purposes; if the percentage of employed ethnic minorities changes and affects the levels of land rent exemption or reduction determined by the competent authorities, the employing organizations or units must comply with the provisions in point g of this clause so that the tax authorities can decide to adjust the land rent exemption or reduction as per regulations.
i) In cases where a competent state authority conducts inspections and determines that an employing organization or unit does not employ ethnic minorities, or the percentage of employed ethnic minorities does not meet the percentage required to qualify for land rent exemption or reduction as stipulated in this clause, the authority shall transfer this information to the tax authority to inform the employing organization or unit of the payment of the reduced or exempted land rent as prescribed in Decree No. 103/2024/ND-CP.
6. The land rent exemption or reduction for an organization or unit employing a workforce comprised of people with disabilities (hereinafter referred to as employing organization or unit”) that is leased land by the State with annual land rent payment for production or business purposes shall be as follows:
a) A 50% reduction in land rent within a year shall be granted to the organization or unit employing the workforce comprised of people with disabilities with a percentage (%) of disabilities ranging from 30% to less than 70% as determined according to the provisions set forth in point c of this clause.
b) An exemption from land rent within a year shall be granted to the organization or unit employing a workforce comprised of disabilities with a percentage (%) of disabilities of 70% or more as determined according to the provisions set forth in point c of this clause.
c) The identification of employees with disabilities and the percentage (%) of employed persons with disabilities shall comply with the Disability Law of 2010, Decree No. 28/2012/ND-CP dated April 10, 2012 of the Government detailing and guiding the implementation of certain articles of the amended Disability Law of 2021 and the guiding documents on the implementation of Decree No. 28/2012/ND-CP.
d) The exemption or reduction of land rent is based on the percentage (%) of employed people with disabilities from the year proceeding the year in which the land rent is due.
dd) Within 30 days from the date of the notification of first payment of land rent by the tax authority (May 31 from the second year of the land lease onwards), the employing organization or unit must submit to the tax authority the application for a reduction in land rent in accordance with tax management laws in order to receive a reduction in land rent as stipulated in this clause. In cases of exemption from land rent, the employing organization or unit is not required to carry out procedures to request an exemption from land rent; they only need to provide information about the entity eligible for land rent exemption in accordance with the provisions of this clause to the tax authority no later than 30 days from the date of notification of land rent payment from the tax authority. The tax authority shall, based on the application and information provided by the employing organization or unit, decide the land rent exemption or reduction of the employing organization or unit in accordance with this clause.
e) Annually, if the percentage of employed people with disabilities remains unchanged or changes but does not affect the level of land rent exemption or reduction determined by the competent authority, the employing organization or unit is only required to submit a report on the situation of employment of people with disabilities in the planned year to the tax authority for monitoring purposes; if the percentage of employed people with disabilities changes and affects the level of land rent exemption or reduction determined by the competent authority, the employing organization or unit must comply with the provisions in point dd of this clause so that the tax authority can decide to adjust the land rent exemption or reduction as per regulations.
g) In cases where a competent state authority conducts inspections and determines that the employing organization or unit does not employ people with disabilities, or the percentage of employed people with disabilities does not meet the percentage required to qualify for land rent exemption or reduction as stipulated in this clause, the authority shall transfer this information to the tax authority to inform the employing organization or unit of the payment of the reduced or exempted land rent as prescribed in Decree No. 103/2024/ND-CP.
7. The land rent exemption or reduction shall be granted to a private establishment investing in public services that is entitled to the policy aimed at encouraging the development of private sector involvement as stipulated in Decree No. 69/2008/ND-CP dated May 30, 2008 of the Government regulating policies aimed at encouraging the private sector involvement for activities in the fields of education, vocational training, health care, culture, sports, and environment, which was amended in 2014, and Decision No. 1466/QD-TTg dated October 10, 2008 of the Prime Minister providing a detailed list of types, criteria, scales and standards of private establishments investing in public services in the fields of education – training, vocational training, health care, culture, sports, and environment, which was amended in 2013 and 2016 (except for projects within which land rents are exempted or reduced as provided in point a, clause 1, Article 157 of the 2024 Land Law and specified in clause 15, Article 38 of Decree No. 103/2024/ND-CP).
Based on the actual local conditions, the provincial People’s Committee shall propose to the provincial People’s Council to make a decision on the specific level of land rent exemption or reduction for the private establishment investing in public services (which have private sector involvement projects that are approved by competent state agencies in accordance with the law but are not included in projects entitled to land rent exemption or reduction as stipulated in point a of clause 1, Article 157 of the Land Law of 2024) and are leased land by the State to carry out private sector involvement projects, the contents of which have been approved to be included in the list of types, criteria, scale, and standards for private sector involvement specified in Decision No. 1466/QD-TTg of the Prime Minister), in principle, not exceeding the preferential regime issued under the provisions of clause 15, Article 38 of Decree No. 103/2024/ND-CP, as follows:
a) The minimum land rent exemption shall comply with the provisions of Clause 3, Article 39 of Decree No. 103/2024/ND-CP; the maximum land rent exemption shall be the total land rent for the entire land lease term. The land user shall not include the exempted land rent in the cost of products or services provided to society.
In cases of land rent exemption or reduction, the time for exemption or reduction shall start from the date of the decision to lease the land or the decision to permit the land repurposing to implement the private sector involvement project by the competent state authority. In cases where the private establishment investing in public services eligible for a reduction in land rent does not or delays the procedures to obtain the land rent reduction, the implementation shall be in accordance with the provisions of Clause 1, Article 38 of Decree No. 103/2024/ND-CP.
b) In the event that after the project is completed and put into operation, the competent state authority conducts an inspection and determines which private establishment investing in public services does not comply with the regulations on types, criteria, scales or standards of private sector involvement as stipulated in Decision No. 1466/QD-TTg issued by the Prime Minister, according to the committed contents, the private establishment investing in public services must pay the land rent that was exempted or reduced in accordance with policy as well as the land rent at the time of the written exemption or reduction issued by the competent state authority, along with any late payment interests calculated on the exempted or reduced land rent according to the laws on tax management.
In the event that after the construction project has been completed and put into operation, the competent state authority conducts inspections and determines which private establishment investing in public services does not meet the regulations on the list of types, criteria, scales or standards stipulated in Decision No. 1466/QD-TTg of the Prime Minister due to amendments, supplements or replacements made to this list, or during the course of operation where the competent authority changes the administrative boundaries, upgrading from a non-urban administrative area to an urban area in the area where the project is executed, but the private establishment investing in public services still operates correctly and meets the conditions and criteria at the time it was approved by the competent authority for land rent incentives, then the private establishment investing in public services will still be entitled to the approved incentives.
c) Based on the actual situation in the area and the type of private sector involvement project, the provincial People’s Committee shall assign the tax authority to take the lead (in the case of reducing land rent) and the agency performing state management of land to take charge (in the case of exempting land rent) and cooperate with relevant private sector involvement authorities and other relevant agencies in conducting the inspection and determine compliance by the private establishment investing in public services with the regulations on the List of types, criteria, scales or standards of private sector involvement as stipulated in Decision No. 1466/QD-TTg by the Prime Minister at the time of project completion and commencement of operations.
d) The conduct of the inspection and determination as stipulated in points b and c of this clause shall be as follows:
After the project is completed and put into operation, within the time frame specified in the list of types, criteria, scales and standards of each area of private sector involvement as stipulated in Decision No. 1466/QD-TTg of the Prime Minister, or within 30 days from the date the project is completed and put into operation, the private establishment investing in public services must send a documented notification to the tax authorities (in cases of reduction in land rent) and the agency performing state management of land (in cases of exemption from land rent) to inform them that the project has been completed and put into operation, along with relevant documents and materials to verify compliance with the regulations on types, criteria, scales, and standards of private sector involvement as per Decision No. 1466/QD-TTg of the Prime Minister, and to compile a summary of cases granted exemption from land rent as prescribed.
Within 30 days from the date of receiving the notification from the private establishment investing in public services, the tax authority (in cases of reduction in land rent) and the agency performing state management of land (in cases of exemption from land rent) shall cooperate with relevant agencies in carrying out the provisions stipulated in clause c of this clause.
In the event that the project of the private establishment investing in public services does not meet the type, criteria, scale or standards of private sector involvement as specified in Decision No. 1466/QD-TTg by the Prime Minister, the aforementioned agencies are responsible for reporting to the provincial People’s Committee for handling as prescribed in point b of this clause; in cases where the project of the private establishment investing in public services meets the regulations on the list of types, criteria, scales and standards for private sector involvement, the tax authority (in the case of reduction in land rent) and the agency performing state management of land (in the case of exemption from land rent) shall confirm and notify in writing to the private establishment investing in public services and append the information to the records of exemption and reduction.
8. A 50% reduction in land rent shall apply to cases of cooperatives, cooperative unions and cooperative unions that are leased land by the State with annual land rent payments to be used as a production and business base (not applicable to cases specified in point h, clause 1, Article 157 of the 2024 Land Law).
9. The exemption or reduction of land rents in necessary cases to implement socio-economic policies, stabilize the macro economy, support production and business development, ensure social welfare, and address arising issues in the practical management of socio-economic affairs annually shall be carried out as follows:
a) On the basis of the tasks and solutions outlined in the socio-economic development plans issued by the competent authorities or the tasks assigned by the competent authorities, the Ministry of Finance shall submit to the Government regulations on the exemption or reduction of land rents for one year according to the provisions of this clause.
b) The reduction of land rents as stipulated in this clause in the year 2025 shall comply with the provisions of Article 6 of this Decree.
Article 6. Reduction in land rents payable for the year 2025
1. A 30% reduction in land rents payable for the year 2025 shall apply to land users as prescribed in Article 4 of the 2024 Land Law, provided that they are currently leasing land from the State with annual land rent payments (including cases where the land user has or does not have legal documentation concerning the land but is using the land and is required to pay land rent for the year 2025 as stipulated and cases where the land user is using the land but has not completed the land documentation in accordance with land laws).
This regulation in this Article is also applicable to land users who are ineligible for exemption from or reduction in land rents or those whose exemption or reduction periods have expired and those whose land rents are being reduced according to land laws and other related laws.
2. The reduction in land rent for the year 2025 as stipulated in Clause 1 of this Article shall be calculated based on the amount of land rent payable for the year 2025 according to the land rent payment notice (if any) or shall be calculated in accordance with the legal regulations on land rents in cases where no land rent payment notice has been issued. No reductions shall be made on the outstanding land rents from previous years before 2025 and any late payment interests (if applicable). In case a land user is being given a reduction in land rents as prescribed and/or a deduction of compensation and ground clearance support under regulations of law on land rents, the reduction in land rent specified in clause 1 of this Article shall be calculated on the land rent payable (if any) after reduction and/or deduction as per regulations of law (except for land rents that have been reduced for the year 2024 according to the provisions of Decree No. 87/2025/ND-CP dated April 11, 2025 of the Government on land rent reduction for the year 2024).
3. Within 30 days from the date of a decision to reduce the land rent for 2025 as stipulated in this Article, the project developer leased land by the State with annual land rent payment to invest in the construction and operation of infrastructure in industrial parks, industrial clusters or export processing zones (hereinafter referred to as “project developer”) shall be required to allocate the reduced land rent for the area of land that has been sub-leased by the project developer in accordance with the provisions of Clause 6, Article 202 of the 2024 Land Law (allocated evenly according to the ratio of the area of land that has been leased to the subjects as specified in Clause 6, Article 202 of the 2024 Land Law). The reduced land rent for the area of land that has not been sub-leased does not require the project developer to allocate. In the event that the project developer does not comply with the provisions of this clause, they shall not be entitled to the policy for reduction of land rent as stipulated in this Article and must adhere to the regulations set forth in point c of clause 5 of this Article.
4. Applications for land rent reduction for the year 2025
An application for land rent reduction for the year 2025 is the original written request for reduction in land rent for the year of 2025 using the Form in the Appendix enclosed herewith. The land user shall be responsible before law for the truthfulness and accuracy of the information provided, the application form and his/her eligibility for reduction in land rents according to regulations herein.
5. Procedures for reduction in land rents for the year 2025
a) A land user shall submit 01 written request for reduction in land rent as prescribed in clause 4 of this Article in person, by post, by electronic means, via the online public service portal or by other methods in accordance with tax administration laws to a tax authority or another agency in accordance with land laws, tax administration laws from the effective date of this Decree to November 30, 2025 inclusive. The provisions of this Decree regarding the reduction in land rents for the year 2025 shall not apply in cases where land users submit applications after November 30, 2025.
b) Based on the written request for reduction in land rent submitted by the land user in accordance with the provisions of point a of this clause and the Notice of land rent payment for the year 2025 of the land user (if any); within no more than 30 days from the date of receiving the written request for reduction in land rent as stipulated in clause 4 of this Article, the competent authority shall determine the amount of land rent to be reduced and issue a Decision on the reduction in land rent in accordance with land levy and land rent laws and tax administration laws.
c) In case a regulatory authority discovers that a land user is not eligible for land rent reduction in accordance with the provisions of this Article through an inspection or audit after a land rent reduction has been granted by a competent authority or does not comply with the provisions of clause 3 of this Article, the land user must reimburse the State for the reduction granted plus (+) late payment interest thereon as prescribed by tax administration laws. The period for calculating late payment interest shall begin from the time the reduction in land rent is granted until the time the competent state authority decides to retract the amount of rent that has been reduced.
d) If land rent reduction is granted by a competent authority after the land user has paid the land rent for the year 2025, the overpaid rent shall be deducted from the land rent payable in the next period or the next year as prescribed by tax administration laws and other relevant laws. If land rents will no longer be paid, the overpaid rent shall be offset or refunded as prescribed by tax administration laws and other relevant laws.
Article 7. Transitional provisions
1. In cases where a land user is leased land by the State with annual land rent payment; or is allowed to repurpose the land, receive land use extention, adjust land use term, change land use form, recognize land use rights in the case of leasing land with annual land rent payment; uses land for both national defense and security purpose and production and economic development purpose prior to the effective date of this Decree and is now eligible for exemption or reduction of land levy or land rent as stipulated in Clause 2 of Article 4 and Article 5 of this Decree, the exemption or reduction of land levy or land rent shall comply with the provisions of this Decree from the effective date of this Decree. In the event that the land user has not submitted an application for exemption or reduction of land levy or land rent, the following procedures shall be followed:
a) In cases where exemption from land rent is granted, the land user is not required to carry out the procedure for requesting exemption from land rent; they only need to provide information to prove their eligibility for exemption from land rent based on specific circumstances specified in Article 5 of this Decree to the competent authorities in order to implement the decision on land rent exemption as prescribed.
b) In cases where a reduction in land levy or land rent is granted, the land user shall follow the procedures for requesting the reduction in land levy or land rent in accordance with the regulations. In cases where the notice of land levy or land rent payment has been issued in accordance with regulations, the amount of reduction in land levy or land rent shall be determined based on the amount specified in the notice.
2. In cases where land users are eligible for land rent reduction according to the Prime Minister’s Decisions on reducing land rents used for annual socio-economic management (Decision No. 22/2020/QD-TTg, Decision No. 27/2021/QD-TTg, Decision No. 01/2023/QD-TTg, Decision No. 25/2023/QD-TTg) and have submitted valid applications in accordance with legal regulations to the competent state authorities but have not yet received decisions on land rent reduction, the reduced land rent reduction incentives shall be applied and legal regulations prior to the effective date of this Decree shall apply; if the tax authorities have issued notices of land rent payment, the tax authorities shall, based on the notices of land rent payment, determine the amount of land rent to be reduced. Competent state authorities must process the valid applications submitted by land users in accordance with regulations within 90 days from the effective date of this Decree. In case the competent authorities, civil servants or public employees delay the processing of applications, they must be held accountable according to the provisions of law.
Article 8. Effects
1. This Decree comes into force as of August 19, 2025.
2. In case the legislative documents referred to this Decree are amended or replaced, the newest document shall be applied.
3. The regulations on land rent exemption or reduction incentives for production and business establishments employing workforce with disabilities as stipulated in point dd, clause 1, Article 9 of Decree No. 28/2012/ND-CP shall be annulled.
Article 9. Implementation
Ministers, heads of ministerial agencies, heads of Governmental agencies, Chairpersons of people’s committees of all levels and other relevant organizations and individuals shall implement this Decree./.
|
|
ON BEHALF OF GOVERNMENT OF VIETNAM Tran Hong Ha |

